The 2026 INFORMS Conference on Financial Engineering and Fintech will be held on November 6-7, 2026 at Stevens Institute of Technology.
The Microsoft CMT service was used for managing the peer-reviewing process for this conference. This service was provided for free by Microsoft and they bore all expenses, including costs for Azure cloud services as well as for software development and support.
Announcements
Best Paper and Best Student Paper Awards to be issued
CALL FOR PAPERS (CFP) is now open
Earlier registration will be open on August 1, 2026

Conference Overview
The INFORMS Conference will feature the latest developments in financial engineering and fintech. The conference aims to enhance worldwide collaboration and provide an ideal platform for local students and researchers to access leading-edge information.
Conference Location
University Center Complex - TechFlex Conference Center
Stevens Institute of Technology
1 Castle Point Terrace
Hoboken, NJ 07030
Directions and Accommodations
Directions
Please see the directions here
Accommodations
W Hoboken (closest hotel to event): 349.00 - 369.00 USD per night
Last Day to Book : Wednesday, October 14, 2026
Book your group rate for Stevens Institute Of Technology
Sheraton Weehawken (second closest hotel to event): 249.00 - 335.00 USD per night
Last Day to Book : TBA
Book your group rate for Stevens Institute Of Technology (see instructions below)
Select your dates
Click the drop-down arrow under “special rates” on the right
Select "Corp/Promo Code"
Enter “AZG"
Click view rates

Important Dates
Deadline for special session proposals - July 10, 2026
Deadline for regular paper submission - July 10, 2026
Notifications of acceptance - July 31, 2026
Conference dates - November 6–7, 2026
Conference Awards
We are happy to announce the following awards, sponsored NSF CRAFT & RCQF-HKPU:
Best Conference Paper - $1,000 (Will be determined by the Scientific Committee)
Early Career Award - $1,000 (Requirement for the award)
Paper Submission
Please use this LaTeX template to format your paper submission. If you want to be considered for the Best Conference Paper award, you should submit a full paper (maximum 35 pages). Otherwise, regular submission as a short paper with 8 pages will be sufficient.
Paper Submission Portal
Submit your paper via Microsoft CMT
Publication Opportunities
Authors of outstanding accepted conference papers will be invited to submit their work to Management Science (FT50/UT24) and will be granted an additional opportunity to resubmit in the event of an initial rejection.
The dual submission follows the following two steps:
The first stage is the conference submission. Only short or full papers accepted for presentation at the conference will qualify for the dual submission process.
The second stage takes place after the conference. The authors of selected papers will have two weeks to incorporate feedback received during the conference and submit a revised full paper for consideration. The Scientific Committee will then conduct the final evaluation and selection of papers for submission to Management Science.
Keynote Speakers
Andrei Kirilenko – Professor of Finance, Founding Director of the Cambridge Centre for Finance, Technology and Regulation (CCFTR), University of Cambridge
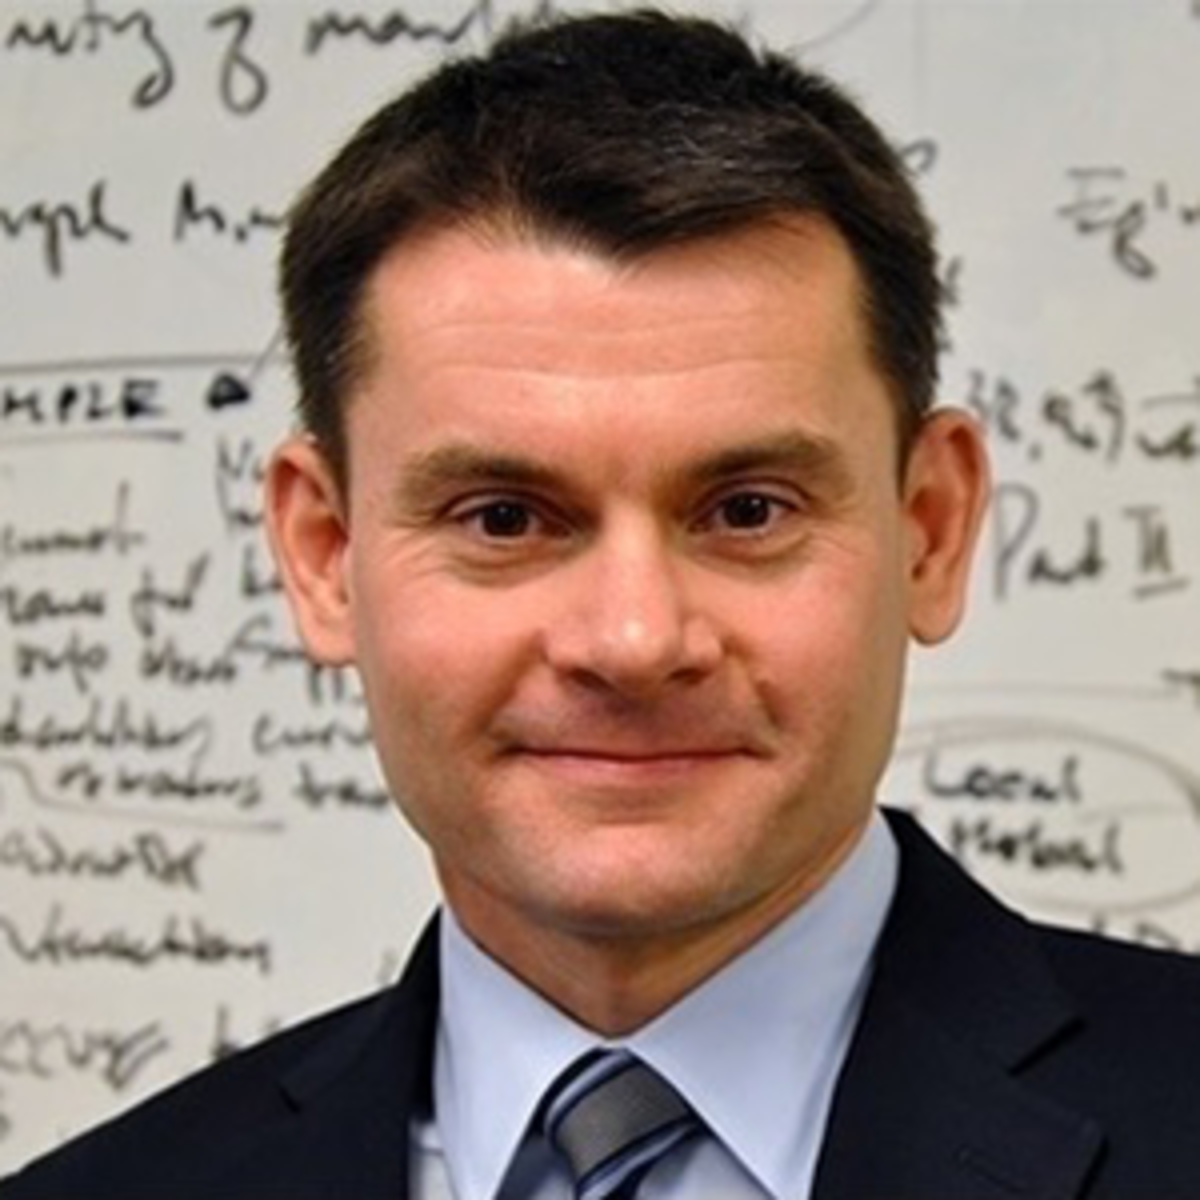 Andrei’s research interests include the intersection of finance, technology and regulation, fintech, asset pricing, data, digital technologies and the design of automated financial markets. He has previously served as Chief Economist of the US Commodity Futures Trading Commission (CFTC), where he used modern analytical tools and methods to design and enforce an effective regulatory regime of financial markets. Andrei is a member of the Finance subject group at Cambridge Judge Business School, which focuses on the investment and financial decisions of institutions.
Jianqing Fan - Frederick L. Moore '18 Professor of Finance, Princeton University
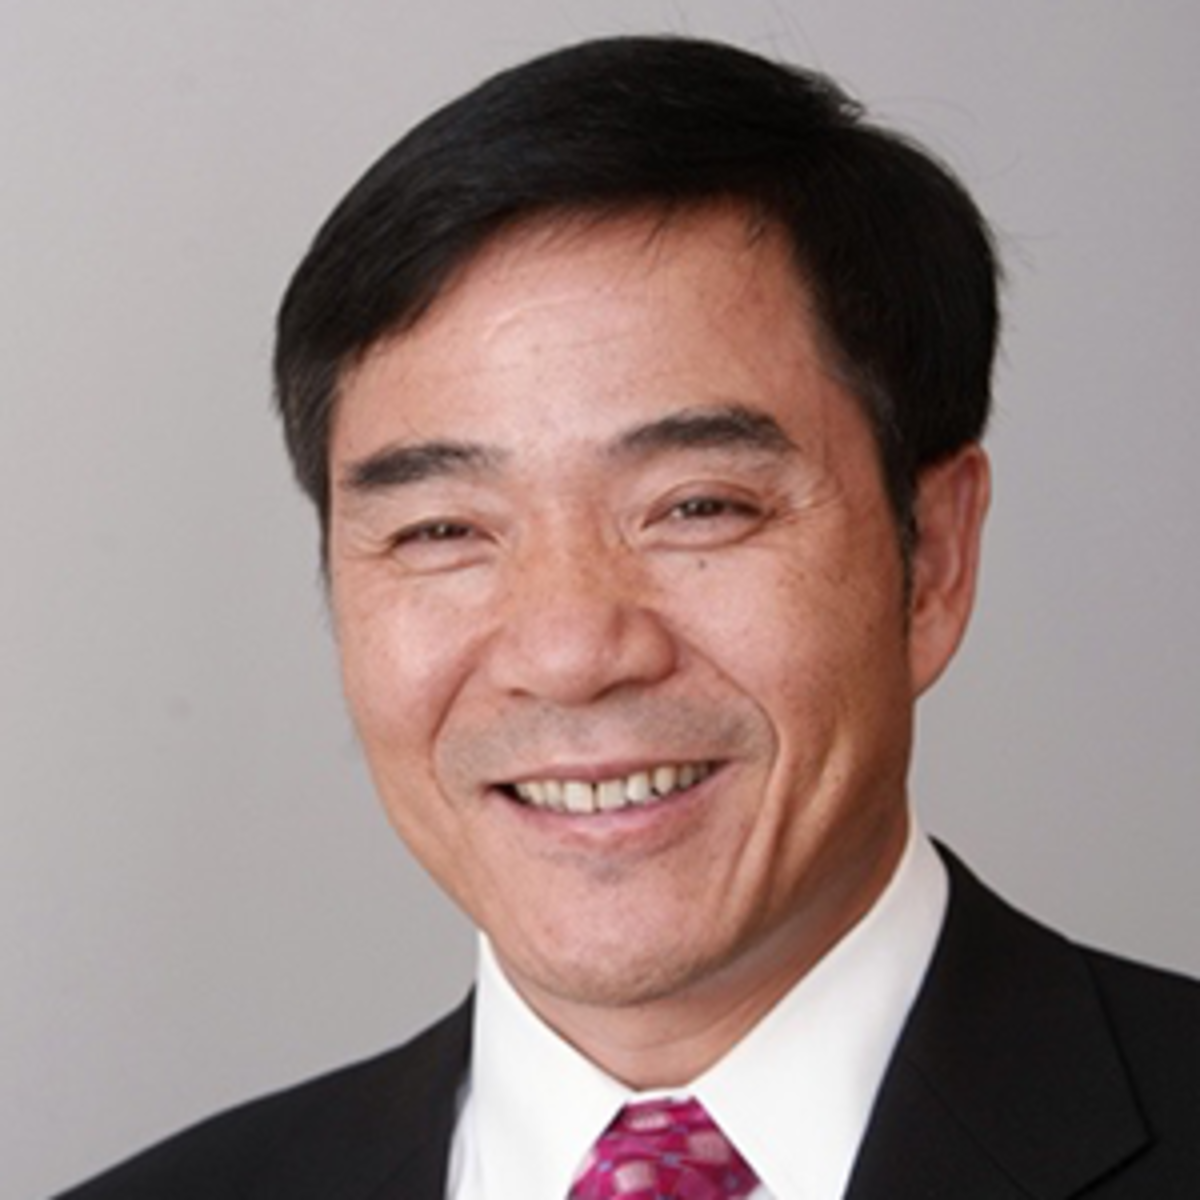 Jianqing Fan is a statistician, financial econometrician, data scientist and AI researcher. He is Frederick L. Moore '18 Professor of Finance, Professor of Statistics and Professor of Operations Research and Financial Engineering at Princeton University, where he chaired the department from 2012 to 2015. He is the recipient of the 2000 COPSS Presidents' Award, Morningside Gold Medal for Applied Mathematics (2007), Guggenheim Fellow (2009), Pao-Lu Hsu Prize (2013), Guy Medal in Silver (2014), Noether Distinguished Scholar (2018), Le Cam Award and Lectures (2021), and Wald Memorial Award and Lectures (2025), the highest honor bestowed by the Institute of Mathematical Statistics. He was elected as an Academician from Academia Sinica (中央研究院院士) in 2012, the Royal Flemish Academy of Belgium (比利时皇家科学院院士)in 2023, National Academy of Sciences (美国国家科学院院士) in 2026.
Manuela Veloso - J.P. Morgan AI Research and Herbert A. Simon University Professor Emeritus, Carnegie Mellon University
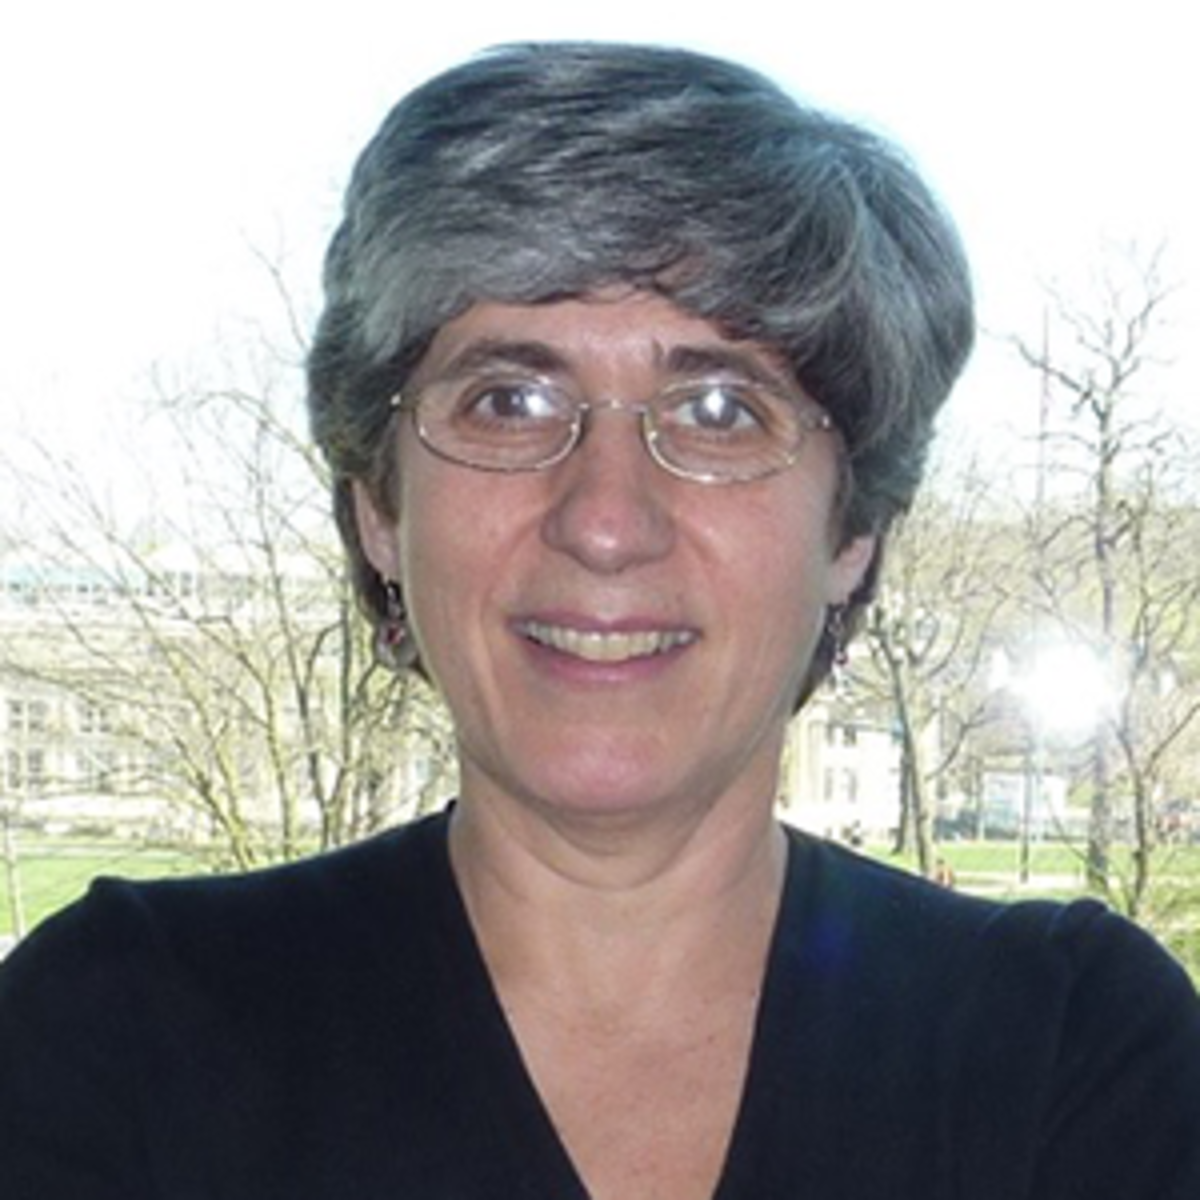 Manuela is the Head of J.P. Morgan AI Research & Herbert A. Simon University Professor Emeritus in the School of Computer Science at Carnegie Mellon University, where she was previously Head of the Machine Learning Department. She served as president of Association for the Advancement of Artificial Intelligence (AAAI) until 2014 and is the co-founder and a Past President of the RoboCup Federation. She is a fellow of AAAI, Institute of Electrical and Electronics Engineers (IEEE), American Association for the Advancement of Science (AAAS) and Association for Computing Machinery (ACM). She is an international expert in artificial intelligence and robotics.
Paul Glasserman - Jack R. Anderson Professor of Business, Columbia University
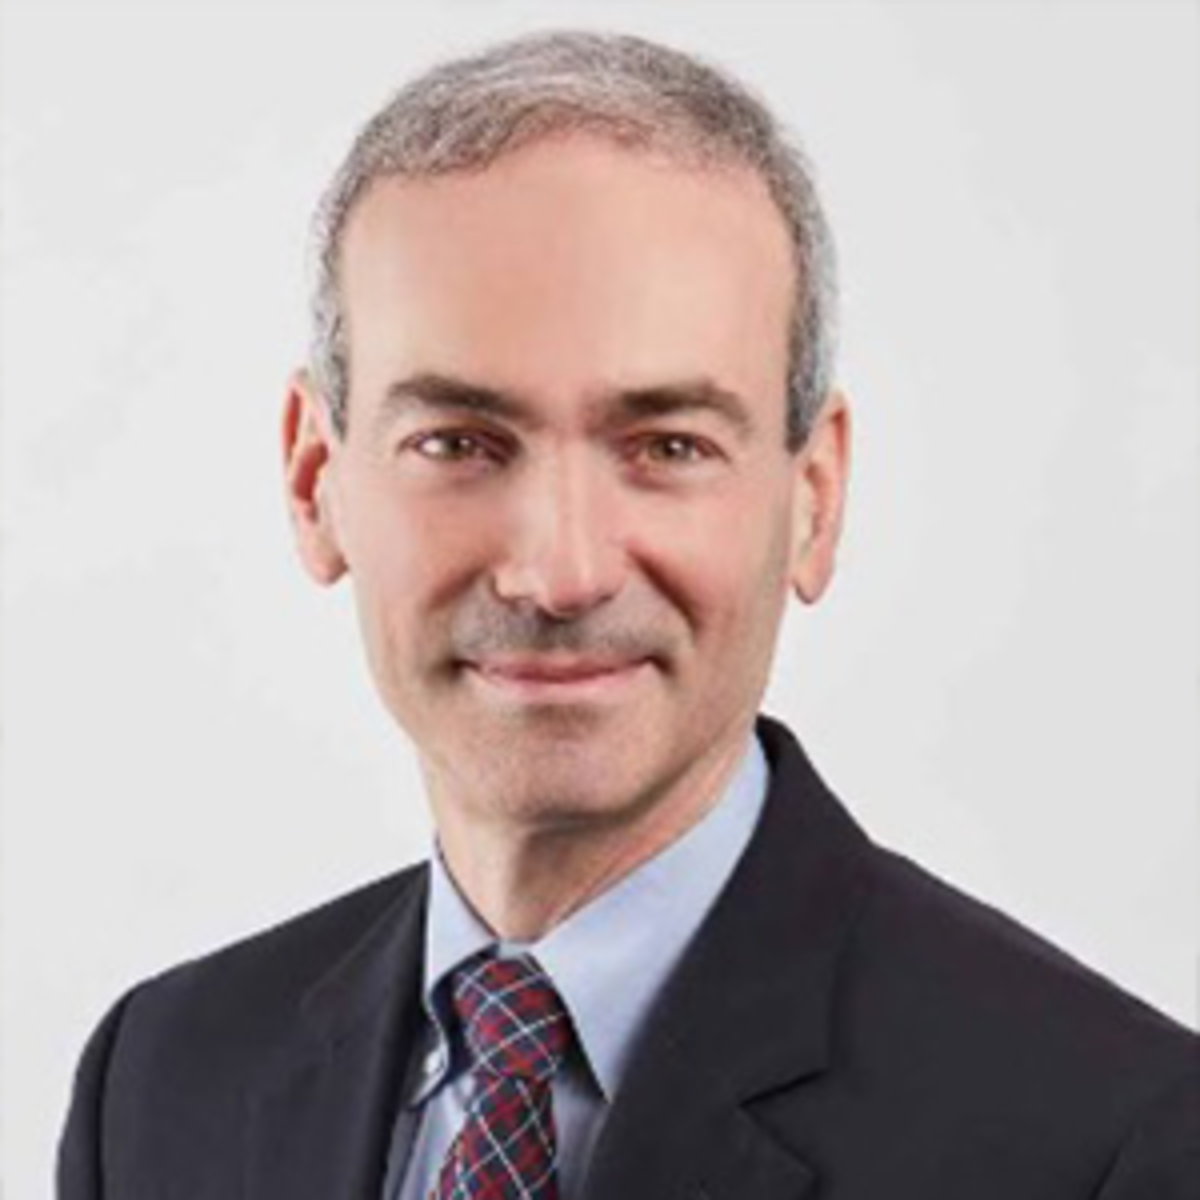 Professor Glasserman's research and teaching address risk management, quant finance, Monte Carlo simulation, statistics and operations. Prior to joining Columbia, Glasserman was with Bell Laboratories; he has also held visiting positions at Princeton University, NYU and the Federal Reserve Bank of New York. In 2011-2012, he was on leave from Columbia and working at the Office of Financial Research in the U.S. Treasury Department, where he continues to serve as a part-time consultant. Paul was named the 2020 Financial Engineer of the Year by the International Association for Quantitative Finance. His publications include the book Monte Carlo Methods in Financial Engineering (Springer, 2004), which received the 2006 Lanchester Prize and the 2005 I-Sim Outstanding Publication Award.
Ning CAI - Professor of Financial Technology, Hong Kong University of Science and Technology – Guanzhou
 Ning Cai is currently professor and thrust head of the Thrust of Financial Technology at the Hong Kong University of Science and Technology (Guangzhou) (HKUST[GZ]). He is also serving as the director of the Guangzhou Municipal Key Laboratory of Financial Technology Cutting-Edge Research. Previously, he taught in the Department of Industrial Engineering and Decision Analytics (IEDA) at HKUST as assistant professor, associate professor and professor sequentially. He was the first Academic Director of the Master of Science Program in Financial Technology (MSc in FinTech) at HKUST, which is jointly offered by School of Business and Management, School of Engineering and School of Science. He also served as the Director of the Financial Engineering and FinTech Laboratory in the Department of IEDA at HKUST.
Scientific Committee Members
Min Dai (Committee Chair), Hong Kong Polytechnic University
Steve Yang (Local Organizer), Stevens Institute of Technology
Agostino Capponi, Columbia University
Lin William Cong, NTU and Cornell University
Zach Feinstein, Stevens Institute of Technology
Kay Giesecke, Stanford University
Martin Haugh, Imperial College
Xuedong He, Chinese University of Hong Kong
Steven Kou, Boston University
Renyuan Xu, Stanford University
Local Organizing Committee
Douglas Cumming, Stevens Institute of Technology
Zach Feinstein, Stevens Institute of Technology (Co-Chair)
Ionut Florescu, Stevens Institute of Technology
Steve Yang, Stevens Institute of Technology (Co-Chair)

