Financial Engineering Seminar: Bootstrapping Option Risk Premiums
Abstract
The talk proposes a bootstrapping procedure for estimating conditional option return risk and option risk premium. Applying the procedure to currency options shows that mean-variance option investment based on the bootstrapped risk and risk premium generates high risk-adjusted returns. Attributing the bootstrapped risk and risk premium to classic risk factor structures highlights the time-varying contribution of each risk source and identifies highly profitable factor timing investment opportunities. Incorporating the bootstrapped option risk premium in option pricing model estimation enhances statistical dynamics identification and promotes model designs that capture both the option price behavior and the option risk premium variation.
View the paper here.
Biography
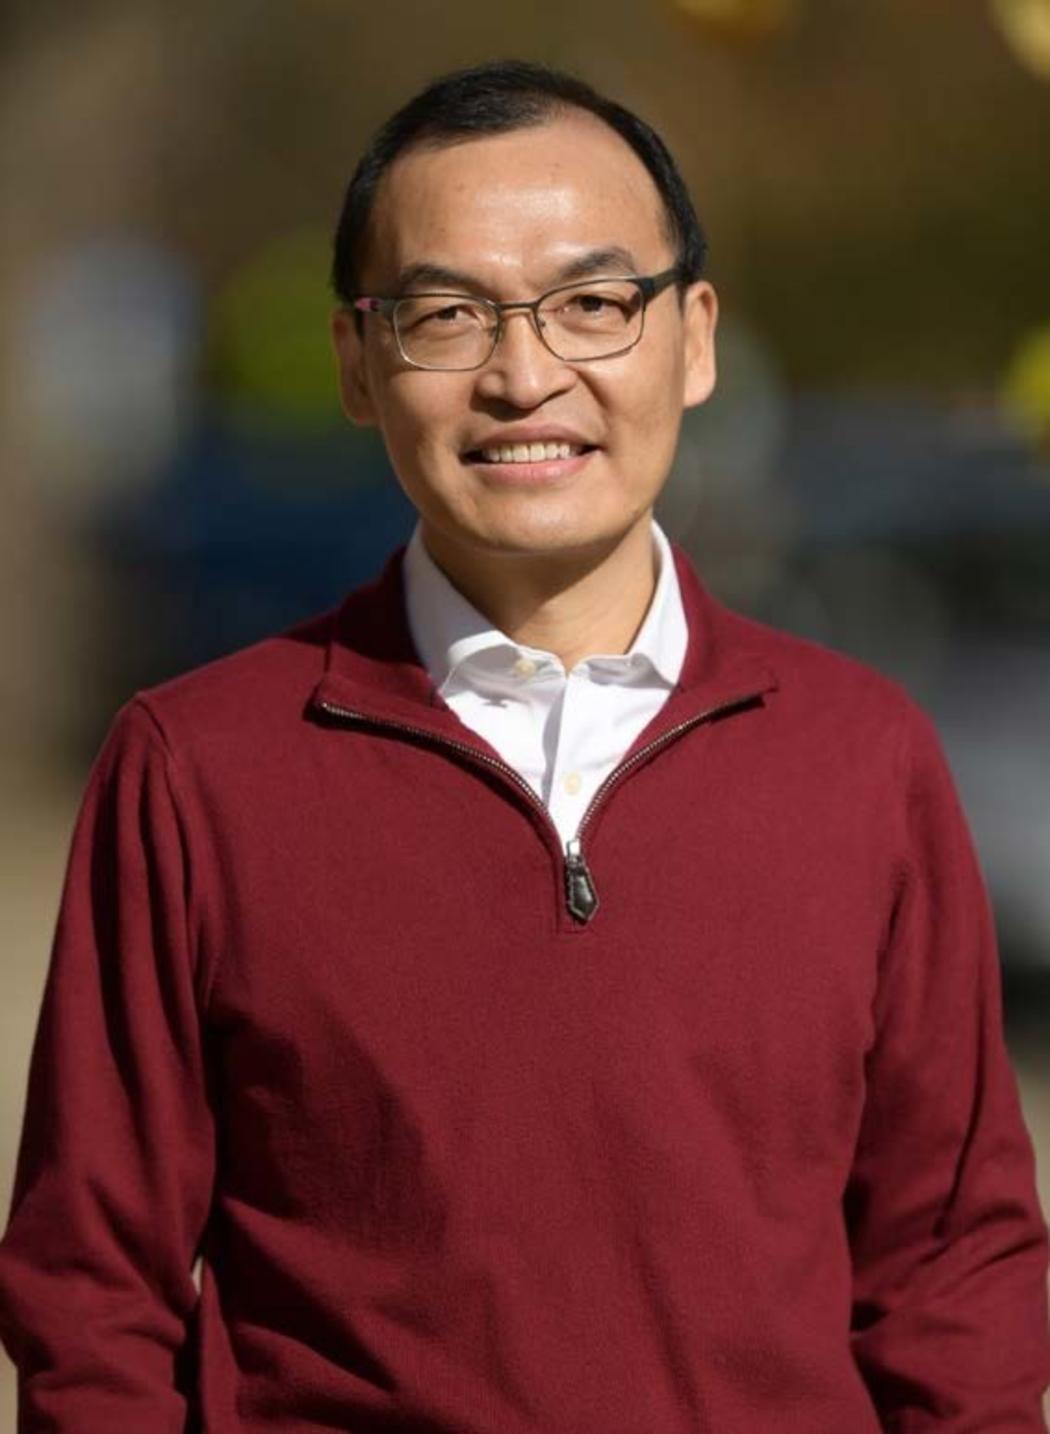
Liuren Wu is the Wollman Distinguished Professor of Finance at Zicklin School of Business, Baruch College, City University of New York. Professor Wu’s research interests span option pricing, credit risk, term structure modeling, market microstructure, and general asset pricing. Professor Wu has published extensively in top finance journals and has built strong working relations with the finance industry, including data vendors, investment banks, market-making firms and hedge funds. He has developed column-based data structures, risk management procedures, trade execution algorithms, market-making platforms, and statistical arbitrage trading strategies.
Discrimination notice: Persons of all identities are invited to and included in this group. Stevens does not discriminate against any person on the basis of sex, race, religion, disability, sexual orientation, gender expression, or any other basis prohibited by law.
Photo and video notice: At any time, photography or videography may be occurring on Stevens’ campus. Resulting footage may include the image or likeness of event attendees. Such footage is Stevens’ property and may be used for Stevens’ commercial and/or noncommercial purposes. By registering for and/or attending this event, you consent and waive any claim against Stevens related to such use in any media. See Stevens' Privacy Policy for more information.